Empty Houses: The Long Arithmetic of a Season Without Crowds
Matchday income is the smallest of the three major revenue pillars and the most expensive to lose, because it is the only one that carries the venue’s fixed cost base with it.
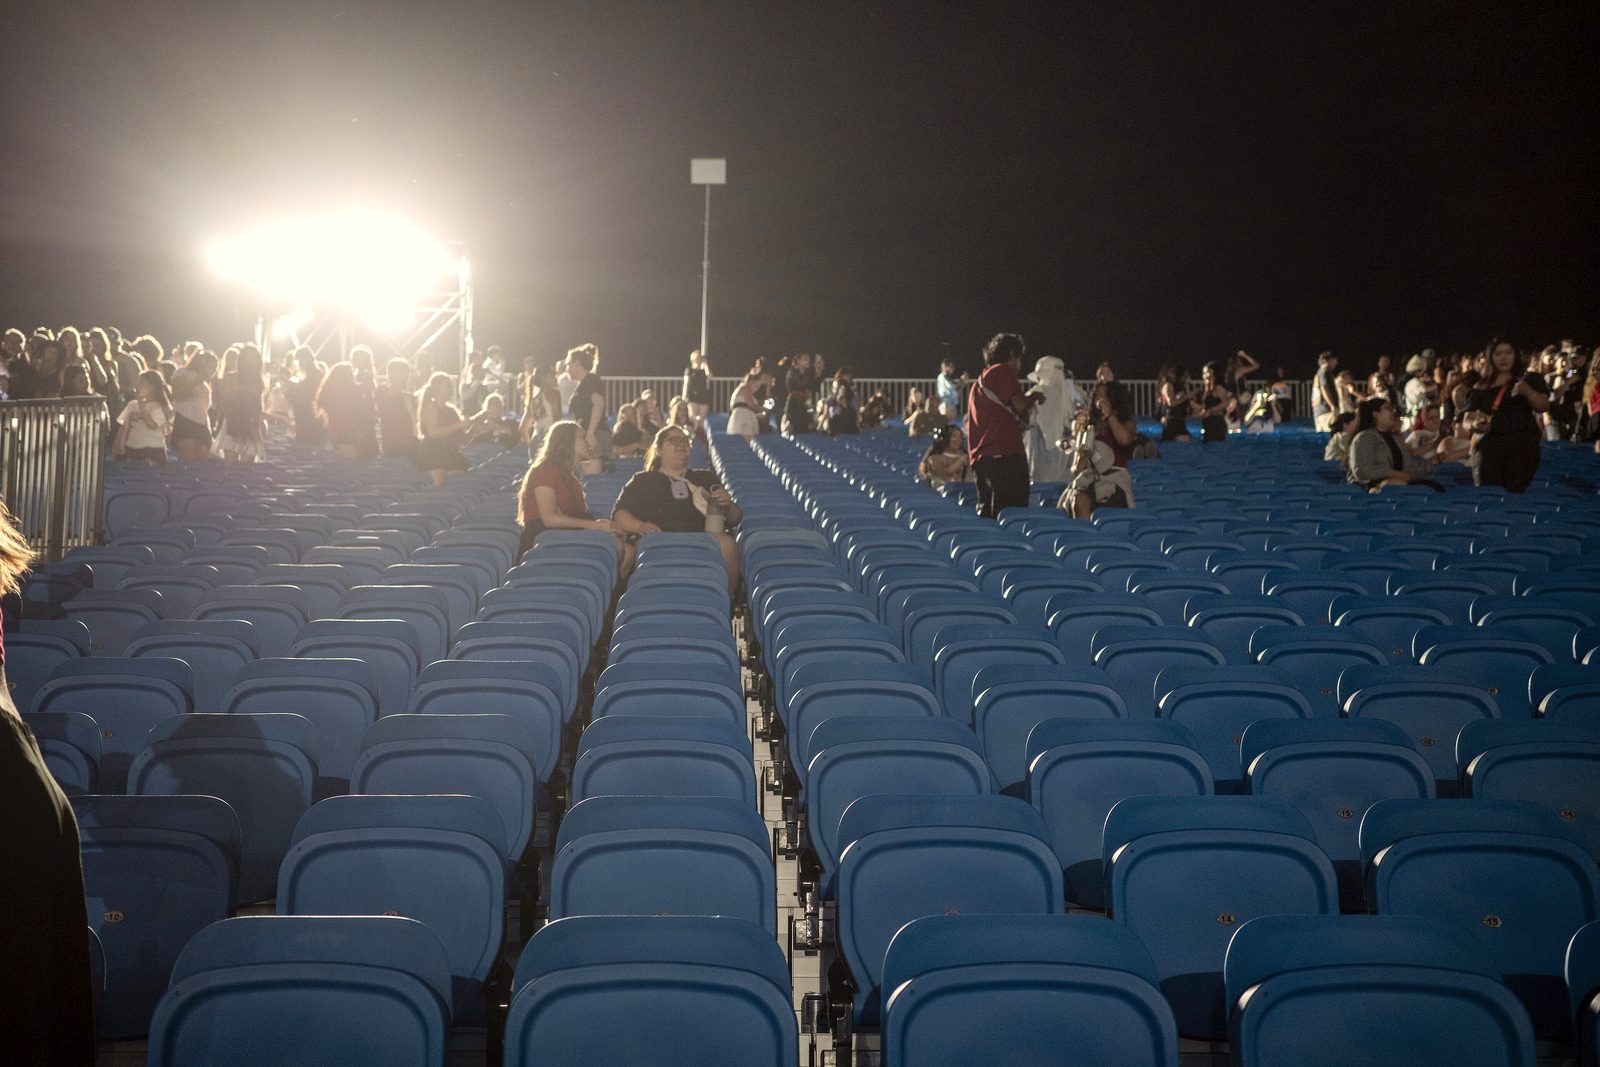
Photograph: Kyy0602 · CC0 · Wikimedia Commons
There is a persistent misreading of what closed-door football costs a club, and it comes from looking at the wrong line. Matchday revenue is routinely reported as somewhere between fifteen and twenty per cent of turnover at a large European club — significant, but not obviously existential next to broadcast income. The figure is accurate and the conclusion drawn from it is wrong.
Matchday is the revenue line that pays for the building. Broadcast and commercial income arrive whether or not the venue opens; the stadium’s operating costs, its staffing, its maintenance cycle and, critically, its debt service, are underwritten in most financial models by attendance receipts. Removing eighteen per cent of revenue while retaining one hundred per cent of the cost it was covering is not an eighteen per cent problem.
The margin is in the boxes
Within matchday, the distribution of profit is heavily skewed. General admission ticketing is a high-volume, low-margin business once stewarding, policing, transport contribution and safety compliance are properly allocated. At several large venues the marginal contribution of a standard seat, fully costed, is thin enough that clubs have historically treated general admission as an audience-building exercise that roughly pays for itself.
The margin sits in premium: hospitality boxes, club seats, and the multi-year corporate agreements attached to them. These are typically sold on three-to-five-year terms, invoiced annually in advance, and carry gross margins several times those of general admission. They are also the inventory most exposed to a closed-door season, because their value is entirely experiential and their buyers are corporate entities that are themselves reviewing discretionary spend.
A stadium without a crowd is not a dormant asset. It is an operating cost with the revenue removed.
Where the debt sits
The financing structures behind the last two decades of stadium construction make this materially worse. Large venue projects are frequently funded through facilities secured against identifiable, recurring receipts, and ticketing and hospitality income are the receipts most commonly pledged. The logic was sound: attendance at an established club is among the most predictable revenue streams in the business, with decades of data behind it.
That predictability is exactly what has now broken, and it has broken in a way the covenants did not anticipate. Several stadium financings carry debt-service coverage ratios calculated against matchday receipts specifically, rather than against total club revenue. Clubs in that position are not merely losing income; they are approaching technical covenant breaches on facilities that remain perfectly serviceable from a whole-business perspective. A number of waivers have already been sought, and lenders have granted them, but waivers are priced.
| Category | Share of matchday revenue | Approx. gross margin |
|---|---|---|
| General admission | 46% | Low |
| Premium seating & hospitality | 34% | High |
| Food, beverage & concessions | 13% | Moderate |
| Retail & matchday merchandise | 7% | Moderate |
| Indicative model. Margins are directional and vary widely by venue ownership structure. Arena Journal estimates. | ||
The non-football calendar
One category of loss has gone almost entirely unreported because it does not appear in football accounts at all. Modern large venues are built to be used well beyond their anchor tenant’s fixture list — concerts, conferences, exhibitions, secondary sporting events. For venues with genuinely diversified programming, the non-anchor calendar can approach or exceed matchday contribution.
That calendar has not been suspended. It has been cancelled, and in the live-music case it has been cancelled further into the future than sport has, because touring schedules are built eighteen months ahead. Venues that spent the last decade justifying their construction cost on the strength of multi-use programming are discovering that diversification into adjacent live-event categories is not diversification at all. Every one of those categories fails in the same conditions, at the same time, for the same reason.
What returns, and in what order
The recovery sequence matters for planning and it is not intuitive. General admission demand is expected to return quickly once permitted, because it is driven by individual discretionary decisions that can be made late. Premium hospitality is likely to lag substantially, because it is driven by corporate budget cycles set months in advance, and because the clients most associated with it — financial services, professional services, corporate entertainment budgets generally — are the ones under the most sustained cost scrutiny.
That inversion is the planning problem for the next three years. Clubs will get their crowds back before they get their margin back, and the interim period — full stadium, depressed premium yield, restored operating cost — may be financially harder than it looks from the terraces.